Disclaimer
This article is for informational purposes only. Nothing in this article is intended to replace legal advice from a competent attorney or be considered legal guidance for anybody's specific legal situation. Nobody should rely on information in this article in making legal decisions without such consultation.
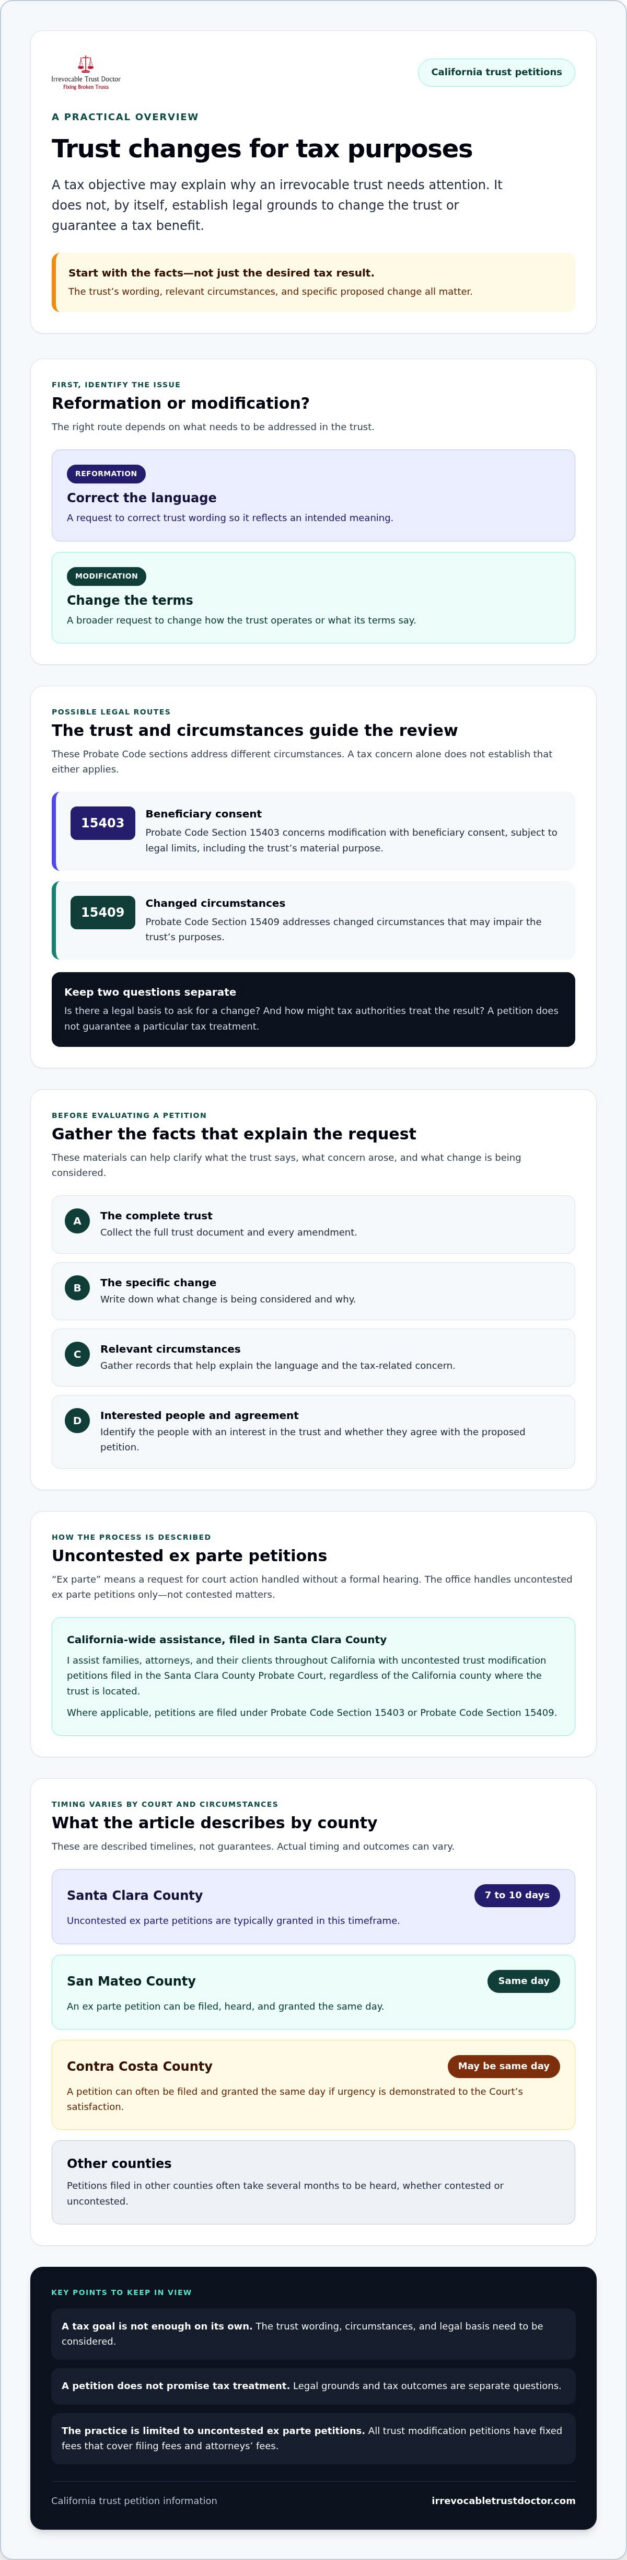
A tax objective may explain why an irrevocable trust needs attention, but it doesn’t automatically give a court grounds to change the trust or guarantee a tax benefit. For families researching trust reformation for tax purposes California, the key question is whether the specific facts support a petition, not simply whether a different tax result would be preferable.
You may also be unsure whether you need reformation or modification, or what documents could help explain the trust’s intent and circumstances. This article outlines what to consider, how an uncontested ex parte petition works, and what to discuss in a focused consultation. I assist families, attorneys, and their clients throughout California with uncontested trust modification petitions filed in Santa Clara County under Probate Code Sections 15403 and 15409, where applicable, regardless of where the trust is located.
Key Takeaways
- For trust reformation for tax purposes California, first identify whether the concern involves correcting language or changing how the trust operates.
- Review the trust and relevant circumstances to assess whether Probate Code Section 15403 or Section 15409 may apply. A tax goal alone doesn’t establish eligibility.
- Prepare the relevant documents and questions before evaluating an uncontested ex parte petition, which proceeds without a formal hearing.
- Families, attorneys, and clients throughout California can discuss an uncontested petition filed in Santa Clara County, regardless of where the trust is located.
What Does Trust Reformation for Tax Purposes in California Mean?
A trust sets out how property is managed and distributed, including the roles of the person who creates it, the trustee who manages it, and the beneficiaries. For a high-level overview, see What is a trust. In general, reformation means asking a court to correct trust language so it reflects an intended meaning. Modification is broader: it means changing the trust’s terms. The distinction matters because the appropriate legal route depends on what needs to be addressed.
A tax concern may prompt a family to consider a petition, but wanting a different tax result doesn’t, by itself, establish legal grounds. A court petition also doesn’t guarantee that tax authorities will treat the trust as intended. The proposed change must be assessed against the trust’s wording, the relevant circumstances, and the legal basis for seeking relief.
Before seeking advice, gather the complete trust document and any amendments. Also collect records that help explain the circumstances behind the language and the proposed change. These materials can help clarify whether the issue appears to involve correcting an expression of intent or changing the trust’s terms. For broader context on California trust changes, see this California trust modification guide.
Does a tax objective alone allow a court to reform an irrevocable trust?
No. The court must have a legal basis to act, and a tax goal alone doesn’t promise relief. When reviewing a possible petition, an attorney will need to consider the trust language, relevant circumstances, and the exact change requested. Those facts help determine whether a petition may be appropriate, but they can’t assure a particular tax treatment.
A petition’s purpose may be tax planning, but its legal grounds and tax outcome must each be assessed separately. That distinction is central to trust reformation for tax purposes California. Start by identifying what the trust says, what problem the language creates, and what specific correction or change is being requested.
When Can a California Court Consider Tax-Related Trust Modification?
California law provides possible routes for asking a court to modify an irrevocable trust, but which route may fit depends on the trust and the facts. Probate Code Section 15403 concerns modification with beneficiary consent, subject to legal limits, including the trust’s material purpose. Probate Code Section 15409 addresses changed circumstances that may impair the trust’s purposes. A tax concern may be part of the circumstances presented, but it doesn’t establish that either route applies or ensure a tax result. The California Probate Code also describes court involvement in trust matters.
When evaluating trust reformation for tax purposes, California families and attorneys should connect the proposed change to the trust’s actual terms and the legal basis for asking the court to act. For more procedural background, review this California probate court petition process.
What should families and attorneys gather before evaluating a petition?
Start with the complete trust and every amendment. Then write down the specific change being considered and why. Gather documents that explain the tax-related concern, and identify the people with an interest in the trust and whether they agree with the proposed petition. These details help counsel assess the circumstances and whether the matter fits an uncontested petition. Our office handles uncontested ex parte petitions only, not contested matters.
I assist families, attorneys, and their clients throughout California with uncontested petitions filed in Santa Clara County, regardless of where the trust is located. A trust petition consultation can help you discuss whether the trust documents, proposed change, and circumstances fit this focused petition practice.
How Does an Uncontested Ex Parte Trust Petition Work in California?
An ex parte petition is a request for court action handled without a formal hearing. I assist families, attorneys, and their clients throughout California with uncontested trust modification petitions filed in the Santa Clara County Probate Court, regardless of where the trust is located. Where applicable, petitions are filed under Probate Code Section 15403 or Probate Code Section 15409.
Timing depends on the court and the circumstances. Santa Clara County petitions are typically granted in 7 to 10 days, but timing and outcomes aren’t guaranteed. In San Mateo County, an ex parte petition can be filed, heard, and granted the same day. In Contra Costa County, that may also happen if the Court is satisfied that urgency has been demonstrated. Petitions in other counties often take several months to be heard.
What are the practical next steps for a tax-focused petition?
For trust reformation for tax purposes California, use a deliberate sequence:
- Gather the complete trust and any amendments.
- Identify the tax-related concern and the specific change being considered.
- Review whether the facts and legal grounds may support a petition, and confirm the matter is uncontested.
- If appropriate, prepare and file the petition, then follow the court’s process.
Our office handles uncontested ex parte petitions only, not contested petitions. All trust modification petitions have fixed fees covering filing fees and attorneys’ fees. Review trust petition fees and costs as you consider next steps. If your matter is uncontested, you can book a trust petition consultation to discuss whether the facts fit this focused practice. A petition does not guarantee a particular tax treatment.
Take the Next Step With a Clear Petition Strategy
A tax concern can prompt a closer look at an irrevocable trust, but it doesn’t establish legal grounds for a court petition or guarantee a particular tax result. For trust reformation for tax purposes California, the trust’s wording, the circumstances, and the specific change requested all matter. Preparing those details can make an initial review more focused.
Robert P. Bergman is a Certified Specialist in Estate Planning, Trust, and Probate Law. He assists families, attorneys, and their clients throughout California with uncontested ex parte trust modification petitions filed in Santa Clara County, regardless of where the trust is located. The practice handles uncontested petitions only.
The practice serves clients across the San Francisco Bay Area, Northern California, Southern California, and the Central Valley, including San Diego, Sacramento, Fresno, Bakersfield, Greater Los Angeles, Orange County, Riverside County, and San Bernadino County. If you’re ready to discuss whether your facts fit this focused petition practice, book a trust petition consultation. A focused review can help identify practical next steps.
Frequently Asked Questions
Can a California court reform an irrevocable trust for tax purposes?
Yes, a California court may consider a petition seeking trust relief for a tax-related reason, but the tax objective alone doesn’t establish legal grounds or guarantee a tax result. For trust reformation for tax purposes California families are considering, the outcome depends on the trust language, surrounding facts, applicable Probate Code provisions, and the specific change requested. A review of the particular circumstances can assess possible routes without promising eligibility.
Does Probate Code Section 15403 or Section 15409 apply to a tax-related trust petition?
Either Probate Code Section 15403 or Probate Code Section 15409 may be relevant, depending on the circumstances and the change being requested. Neither provision applies automatically just because a tax concern exists. A careful review of the complete trust, amendments, relevant facts, and proposed relief is needed to determine which legal pathway, if any, may fit. No tax consequence should be assumed.
Can a trust located outside Santa Clara County be the subject of a petition filed there?
Yes. The practice assists families, attorneys, and clients throughout California and files uncontested ex parte trust modification petitions in Santa Clara County, regardless of the trust’s county location. This includes matters across Northern and Southern California, the San Francisco Bay Area, the Central Valley, San Diego, Sacramento, Fresno, Bakersfield, Greater Los Angeles, Orange County, Riverside County, and San Bernadino County. Eligibility, procedure, timing, and outcome depend on the matter.
How long does an uncontested ex parte trust modification petition take in California?
Timing varies by county and case. Santa Clara County petitions are typically granted in 7 to 10 days, while San Mateo County petitions can be filed, heard, and granted the same day. Contra Costa County petitions can also be handled the same day if the Court is satisfied urgency is demonstrated. These are not guarantees; petitions in other counties often take several months to be heard.
Article by
Robert P. Bergman, Attorney at Law
Attorney Robert P. Bergman ("Bob Bergman") has been a Board-Certified Specialist in Estate Planning, Trust and Probate Law since 2011, as certified by the California State Bar Board of Legal Specialization. For several years, Bob has assisted families and the clients of other attorneys with obtaining court orders through trust modification petitions to make necessary modifications to existing irrevocable trusts. Bob is friendly, very approachable, and believes in explaining complex legal topics in clear ordinary language so that his clients understand exactly what they're doing and why they're doing it.
Bob is often able to assist clients throughout California who are in other counties than his home county of Santa Clara through his approach to trust modification petitions.